Urea (Granular) - Egypt CAS: 57-13-6
Q3 2026 marks the transition from crisis survival to competitive recovery in the chemical industry. Industrial gas leaders, Nutrien, and Indian specialty chemical producers are positioned to outperform, while Gulf producers and European commodity chemical companies face a more difficult quarter ahead.
The Bürgenstock roadmap and recent Hormuz transit data signal a clear path for QAFCO and SABIC to resume ammonia exports in Q3 2026. While force majeure conditions may lift in July, mine clearance delays could postpone full tanker capacity until August. Agricultural and industrial buyers should prepare for an improved but staggered supply outlook.
US ethane export capacity is expanding as Enterprise Products develops new Gulf Coast infrastructure, creating new supply options for Asian ethylene producers. The shift could reduce long-term dependence on traditional naphtha-based feedstock routes.
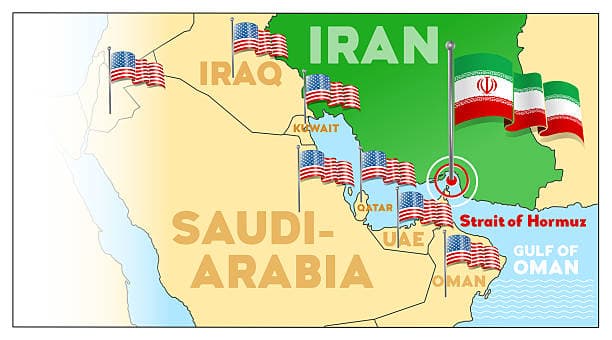
In June 2026, the US chemical scene was jolted by a strategic Hormuz MOU, the disruptive impact of Hurricane Arthur, the landmark Olin‑Huntsman merger, and the sudden INEOS Styrolution plant shutdown. These events reshaped supply chains and market dynamics across North America.
China's petrochemical market entered June 2026 under pressure as weaker seasonal demand and growing supply pushed PE and PP prices lower. For global traders, China's relative price stability amid international volatility is creating new arbitrage opportunities and trade risks worth monitoring closely.
A major wave of new HDPE capacity is entering the market as Chevron Phillips and QatarEnergy prepare to launch their Golden Triangle Polymers facility. The startup could reshape export flows, intensify competition in Asia and improve supply conditions for North American buyers.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.