Overview of the LABSA Landscape in 2026
The detergent chemical market is entering a critical competitive reset phase. Linear alkylbenzene sulfonic acid (LABSA) production depends heavily on linear alkylbenzene (LAB) derived from n‑paraffin refinery streams. Any shift in n‑paraffin supply directly influences LABSA economics and, by extension, detergent surfactant pricing.
Gulf‑Origin n‑Paraffin Supply Chain Recovery
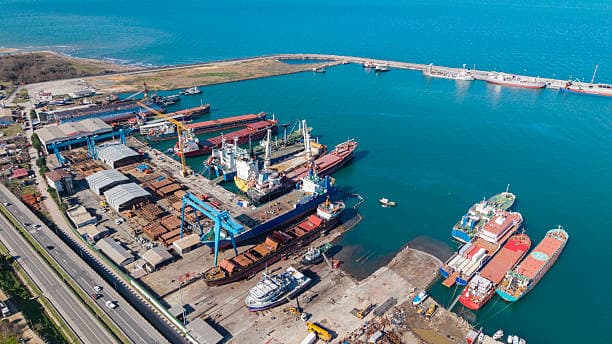
Until early 2026, disruptions in tanker movement from Saudi Arabia and the UAE had forced the industry to rely on alternative sources. The gradual return of Gulf‑origin n‑paraffin cargoes is now reshaping the market. However, residual war‑risk insurance and freight premiums still inflate landed costs, leaving Gulf‑derived LABSA at a potential disadvantage.
Indian Producers Step In
During the first half of 2026, Indian producers such as Indian Oil Corporation Limited (IOCL) and Hindustan Oil Corporation (HOC) expanded LABSA output to fill the supply gaps created by Gulf logistics disruptions. This strategic move allowed them to capture significant market share in Asia and parts of Africa, where detergent manufacturers had been forced to source from more expensive Gulf suppliers.
July Pricing Test: A Benchmarking Opportunity
July has emerged as a critical pricing test. The question is whether Gulf suppliers can regain competitiveness versus Indian‑origin LABSA on a landed‑cost basis. The outcome will hinge on several factors:
Freight and Insurance Costs: Gulf‑origin n‑paraffin still carries higher freight premiums and war‑risk insurance.
Production Efficiency: Indian plants have optimized LABSA synthesis, reducing energy and raw material consumption.
Currency Fluctuations: The rupee’s depreciation has made Indian LABSA more attractive in international markets.
Regulatory Compliance: Gulf suppliers must meet stricter environmental and safety standards, adding to cost.
Competitive Quotes from Both Sides
Detergent manufacturers now face a timely benchmarking opportunity. By comparing competitive quotes from Indian and Gulf suppliers, companies can determine whether the crisis‑era sourcing shift remains economically justified.
Implications for Detergent Manufacturers
For manufacturers, the July pricing test will set a new baseline for sourcing decisions. A few key implications include:
Strategic Sourcing Flexibility: Companies may diversify their supplier base to hedge against future disruptions.
Cost Competitiveness: A favorable landed cost from Indian LABSA could lock in lower detergent prices for end consumers.
Supply Chain Resilience: Reliance on Gulf suppliers may be re‑evaluated if freight and insurance costs remain high.
Market Expansion: Manufacturers in Africa and Southeast Asia may find Indian LABSA more accessible, opening new growth corridors.
Future Outlook for the LABSA Market
Looking ahead, the LABSA market will likely see continued consolidation. Indian producers, with their recent production ramp‑ups, are positioned to maintain a competitive edge if they keep refining operational efficiencies. Gulf suppliers, on the other hand, will need to reduce logistics costs and streamline compliance to regain parity.
Ultimately, the July pricing test will serve as a litmus test for the new equilibrium in the detergent chemical sector. Whether Indian LABSA can sustain its market share or Gulf suppliers can reclaim dominance will depend on how each player navigates the intertwined challenges of supply chain logistics, cost optimization, and regulatory pressures.
For industry stakeholders, staying attuned to these dynamics is essential. By monitoring landed‑cost comparisons and supply chain developments, detergent manufacturers can make informed sourcing decisions that balance cost, reliability, and sustainability.
Linear Alkylbenzene Sulfonic Acid (90%) - India CAS: 27176-87-0