 In 2023, analysts predict that China will import a record amount of crude oil due to rising gasoline consumption as more people travel as a result of the removal of COVID-19 regulations and the startup of new refineries.
The issue is cited from Reuters in early 2023. China's crude imports may rise by 500,000 to 1 million barrels per day (bpd) or more this year, reaching as high as 11.8 million bpd, experts from four industry consultancies, including Wood Mackenzie, FGE, Energy Aspects, and S&P Global Commodity Insight, say, this would reverse a decline from the previous two years, and breaking the previous record of 10.8 million bpd set in 2020. The four consultancies predicted that Chinese refineries will boost oil throughput by 850,000 Due to growing local demand and appealing export markets, production is expected to climb to 1.2 million bpd over 2022 levels, or 6% to 9%.
Another positive development for the oil market will be the expectation of robust demand from the largest importer in the world, which will add to the support already provided by the OPEC+ producing group's output cutbacks and western sanctions against Russian shipments.
China has seen an increase in demand for gasoline and jet fuel when COVID limits were removed in December. Sun Jianan, an analyst at Energy Aspects, predicted that gasoline and jet fuel would be the main drivers of the increase in demand for liquid fuels. By the end of 2023, Sun predicted that jet fuel usage would be 90% higher than it was before COVID.
As per FGE analyst Mia Geng and Energy Aspects' Sun, the rebound in China's manufacturing and real estate sectors will take longer to manifest, which will slow down demand growth for diesel, a crucial industrial and transportation fuel, and naphtha, a petrochemical feedstock.
Refiners will be encouraged to increase runs in order to maintain profitable export cargoes and deliver more feedstocks to the petrochemical industry, analysts said, in addition to meeting the growing domestic demand.
Industry sources predict that two new PetroChina-owned refineries, Guangdong Petrochemical and Jiangsu Shenghong Petrochemical, with a combined capacity of 520,000 bpd, would begin functioning commercially in the coming months.
According to a corporate source, a third greenfield refinery, the 400,000 bpd Shandong Yulong Petrochemical facility, may start importing crude towards the end of 2023 in preparation for potential test runs.
Experts did list several reasons to be wary of demand projections despite all the favorable elements. External hindrances, such as a bleak outlook for the world economy, would put stress on China's export industry. The potential for a COVID virus return and the uncertainty surrounding China's fuel export policy were listed as additional risks by analysts.
References:
Aizhu, Chen & Xu, Muyu. 2022. China set for record crude oil imports in 2023, analysts say. Reuters.
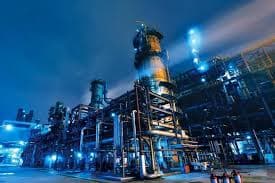
Photo by evening_tao via https://www.freepik.com/
China is On Track to Achieve Significant Increase in Crude Oil Imports in 2023
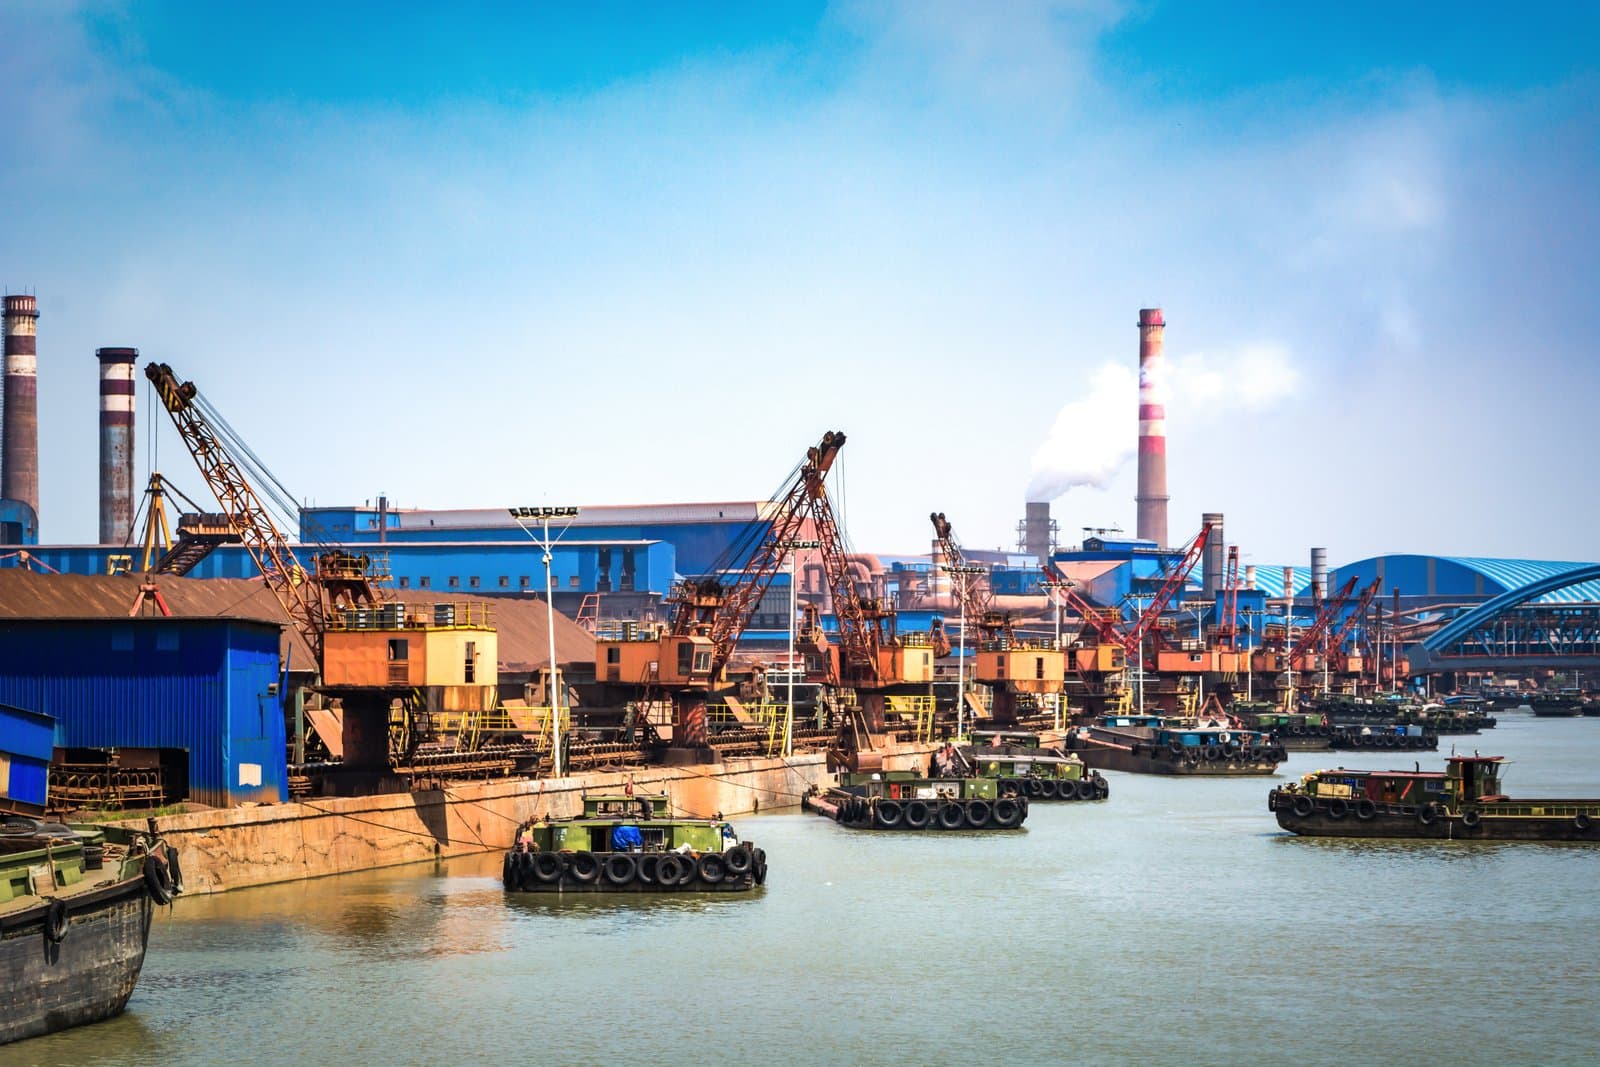 In 2023, analysts predict that China will import a record amount of crude oil due to rising gasoline consumption as more people travel as a result of the removal of COVID-19 regulations and the startup of new refineries.
The issue is cited from Reuters in early 2023. China's crude imports may rise by 500,000 to 1 million barrels per day (bpd) or more this year, reaching as high as 11.8 million bpd, experts from four industry consultancies, including Wood Mackenzie, FGE, Energy Aspects, and S&P Global Commodity Insight, say, this would reverse a decline from the previous two years, and breaking the previous record of 10.8 million bpd set in 2020. The four consultancies predicted that Chinese refineries will boost oil throughput by 850,000 Due to growing local demand and appealing export markets, production is expected to climb to 1.2 million bpd over 2022 levels, or 6% to 9%.
Another positive development for the oil market will be the expectation of robust demand from the largest importer in the world, which will add to the support already provided by the OPEC+ producing group's output cutbacks and western sanctions against Russian shipments.
China has seen an increase in demand for gasoline and jet fuel when COVID limits were removed in December. Sun Jianan, an analyst at Energy Aspects, predicted that gasoline and jet fuel would be the main drivers of the increase in demand for liquid fuels. By the end of 2023, Sun predicted that jet fuel usage would be 90% higher than it was before COVID.
As per FGE analyst Mia Geng and Energy Aspects' Sun, the rebound in China's manufacturing and real estate sectors will take longer to manifest, which will slow down demand growth for diesel, a crucial industrial and transportation fuel, and naphtha, a petrochemical feedstock.
Refiners will be encouraged to increase runs in order to maintain profitable export cargoes and deliver more feedstocks to the petrochemical industry, analysts said, in addition to meeting the growing domestic demand.
Industry sources predict that two new PetroChina-owned refineries, Guangdong Petrochemical and Jiangsu Shenghong Petrochemical, with a combined capacity of 520,000 bpd, would begin functioning commercially in the coming months.
According to a corporate source, a third greenfield refinery, the 400,000 bpd Shandong Yulong Petrochemical facility, may start importing crude towards the end of 2023 in preparation for potential test runs.
Experts did list several reasons to be wary of demand projections despite all the favorable elements. External hindrances, such as a bleak outlook for the world economy, would put stress on China's export industry. The potential for a COVID virus return and the uncertainty surrounding China's fuel export policy were listed as additional risks by analysts.
References:
Aizhu, Chen & Xu, Muyu. 2022. China set for record crude oil imports in 2023, analysts say. Reuters.
Photo by evening_tao via https://www.freepik.com/
Related Insights

EIA's Outdated July Forecast: Why Chemical Companies Should Avoid Single-Scenario Planning
The EIA's July outlook was built around assumptions that changed within weeks after the ceasefire collapsed. Chemical procurement and compliance teams should adopt scenario-based planning to strengthen supply chain resilience in an increasingly unpredictable market.
Baltic Dry Index Drops to Two-Week Low, Straining Bulk Shipping
The Baltic Dry Index slipped to a two‑week low, signaling a slowdown in bulk shipping demand across key commodity fentices. Analysts link the dip to softening steel and grain markets, while chemical logistics firms report rising freight costs. This article examines the underlying forces and what they mean for the dry bulk sector.
Solvay and Searles Valley Cut Soda Ash Capacity: What a Two-Continent Production Retreat Means for Buyers
Capacity reductions by Solvay in Europe and Searles Valley Minerals in California highlight structural changes in the global soda ash market. Procurement teams should understand how supply rationalization could influence pricing, investment and long-term sourcing strategies.
Europe Chemical Watch: Lower Crude, REACH Omnibus, and the VCI's Half‑Year Assessment
The European chemical market enters H2 2026 with Brent crude falling to $72.60, offering temporary input relief amid long‑term capacity cuts. REACH Omnibus moves through Parliament, while the VCI’s German outlook signals further contraction. CBAM Q2 reporting looms on July 15, demanding swift emissions data collection.
Potash 2026: Nutrien Earnings May Signal Q3 Price Direction
Nutrien’s upcoming Q2 2026 earnings are poised to be a pivotal indicator for potash prices in the latter half of the year. Analysts are watching how the data will influence MOP fertilizer demand and the broader potassium chloride market. The market awaits a clear directional signal that could shape pricing strategies worldwide.
Sulfuric Acid Prices Rise in 2026 as Supply Tightness Pushes Regional Markets Higher
Sulfuric acid prices increased across major regions in May 2026 as sulfur availability tightened and supply risks affected global markets. This update examines regional pricing trends and what fertilizer and mining buyers should consider for Q3 planning.
Don't miss out on our updates! Subscribe to our newsletter now
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.