Urea (Granular) - Egypt CAS: 57-13-6
Morocco enters H2 2026 with OCP firmly established as one of the world's most strategically important fertilizer suppliers. The Hormuz disruption strengthened the company's role in global procurement, transforming its Atlantic export route into a long-term competitive advantage.
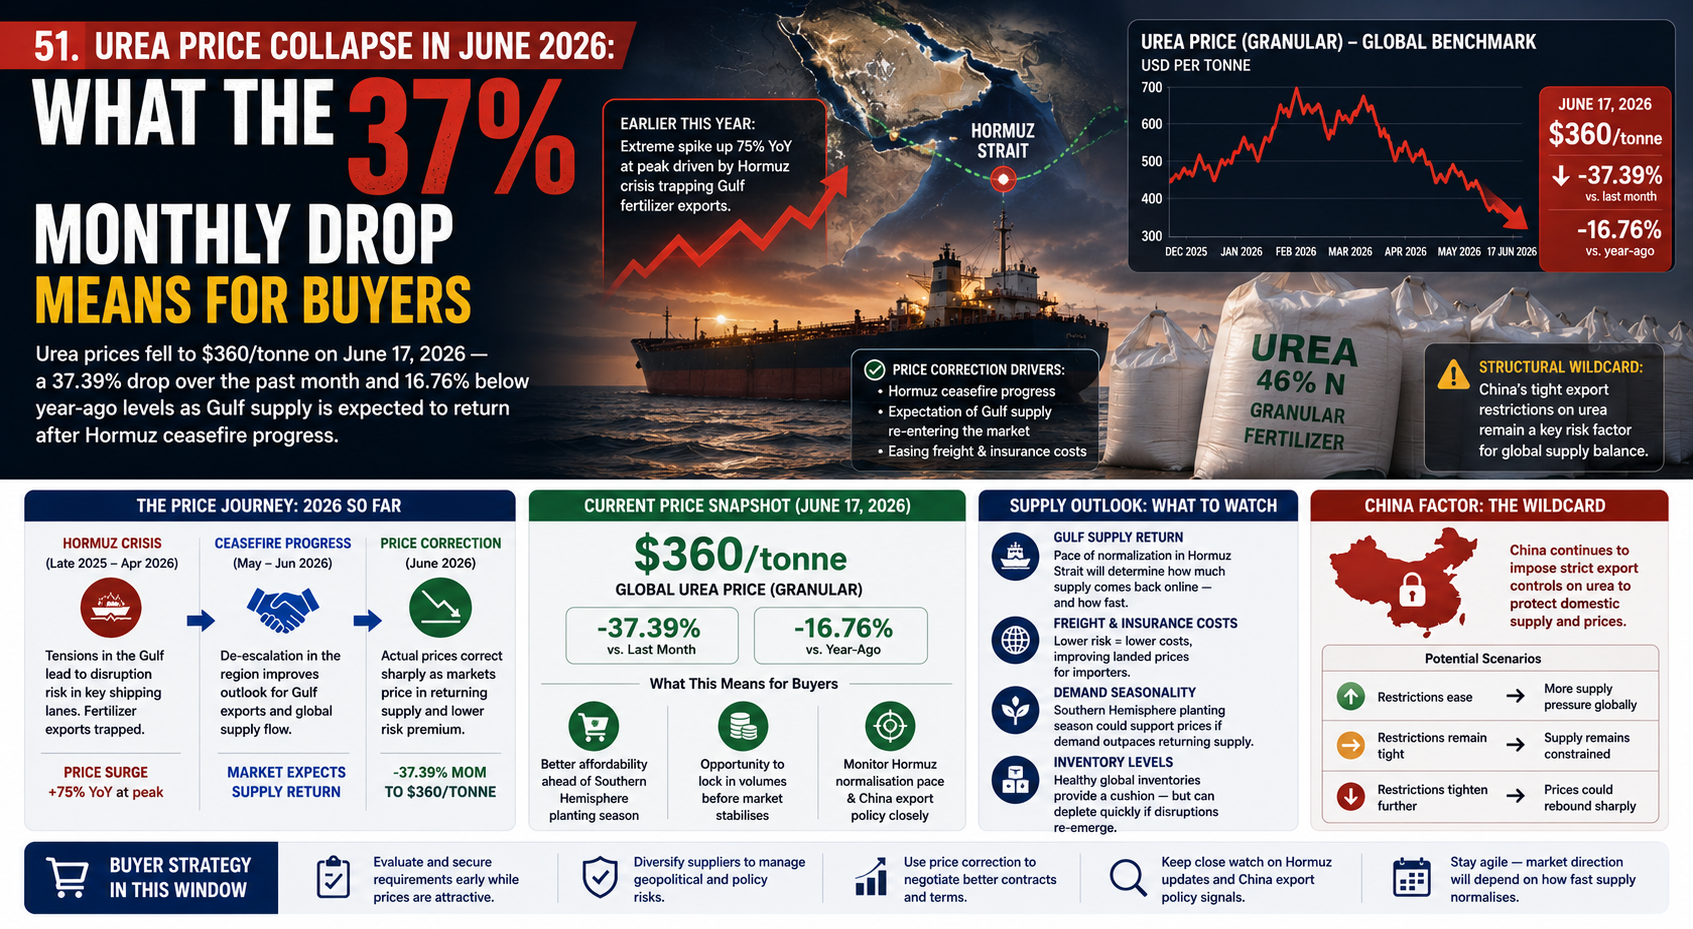
Urea prices in 2026 are poised for a rebound as Gulf exports climb back to 75% of pre‑war levels. This shift reshapes demand in the Southern Hemisphere, offering new buying windows for fertilizer importers. TradeAsia tracks the latest market dynamics for SABIC and QAFCO urea.
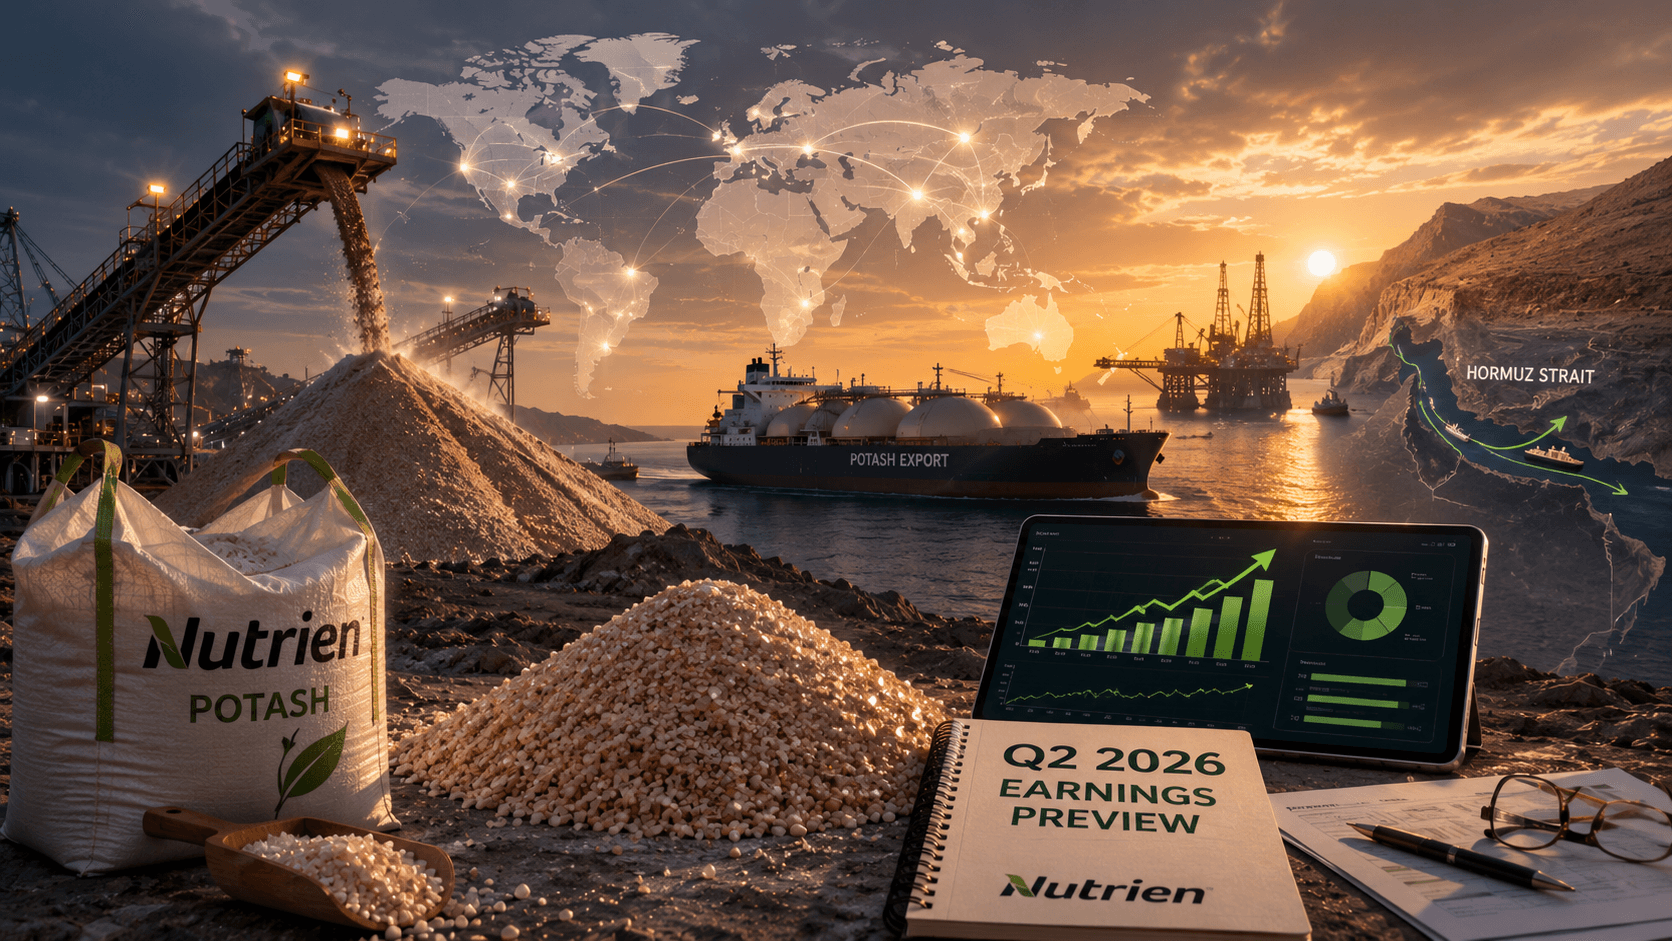
Nutrien is expected to report exceptionally strong Q2 2026 earnings as sanctions on Russian and Belarusian potash combine with Hormuz supply disruption to tighten global markets. Potash buyers should watch July guidance closely before negotiating H2 contracts.

Portfolio restructuring among major specialty chemical companies is creating new procurement considerations for buyers. As asset sales continue across the industry, companies should review supply agreements and strengthen supplier continuity planning for H2 2026.
Palm oleochemical supply chains are improving, but food-grade glycerin buyers should expect continued market tightness through Q3.
The sulfuric acid market is expected to see changing supply conditions as Middle East sulfur availability improves after Hormuz disruptions. Fertilizer and mining buyers should monitor sulfur recovery, energy trends and pricing movements through H2 2026.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.