Related Insights
Saudi Arabia Chemical Watch: H1 2026 Closing Review of SABIC's Ras Tanura Restart
Saudi Arabia's chemical industry closes H1 2026 with SABIC's Ras Tanura terminal restart marking the clearest signal that Gulf petrochemical exports are recovering. As Q3 deliveries resume, international buyers should focus on contract sequencing and supplier engagement rather than assuming immediate spot market availability.
Container Freight Rates in H1 2026: Why Freight Costs Are Unlikely to Return to Pre-Crisis Levels Soon
Container freight markets finished H1 2026 well above pre-crisis pricing despite easing fuel costs. This review explains how Cape of Good Hope routing, carrier commitments and war risk surcharges continue to shape chemical logistics costs for H2 2026.
South Korea Chemical Watch: H1 2026 Closing Review of the Force Majeure Wave
South Korea's petrochemical industry closes H1 2026 after experiencing the most extensive force majeure declarations of any major chemical-producing nation during the Hormuz disruption. As feedstock supplies recover, buyers and suppliers are shifting their focus toward contract resumption and Q3 delivery planning.
Oman's Maritime Services Negotiation: What a Strait of Hormuz Fee System Could Mean for Chemical Logistics
Oman's proposal for maritime-services charges introduces a very different scenario from a geopolitical transit toll. Chemical buyers and logistics teams should understand how each approach could affect freight costs, compliance obligations and long-term sourcing decisions.
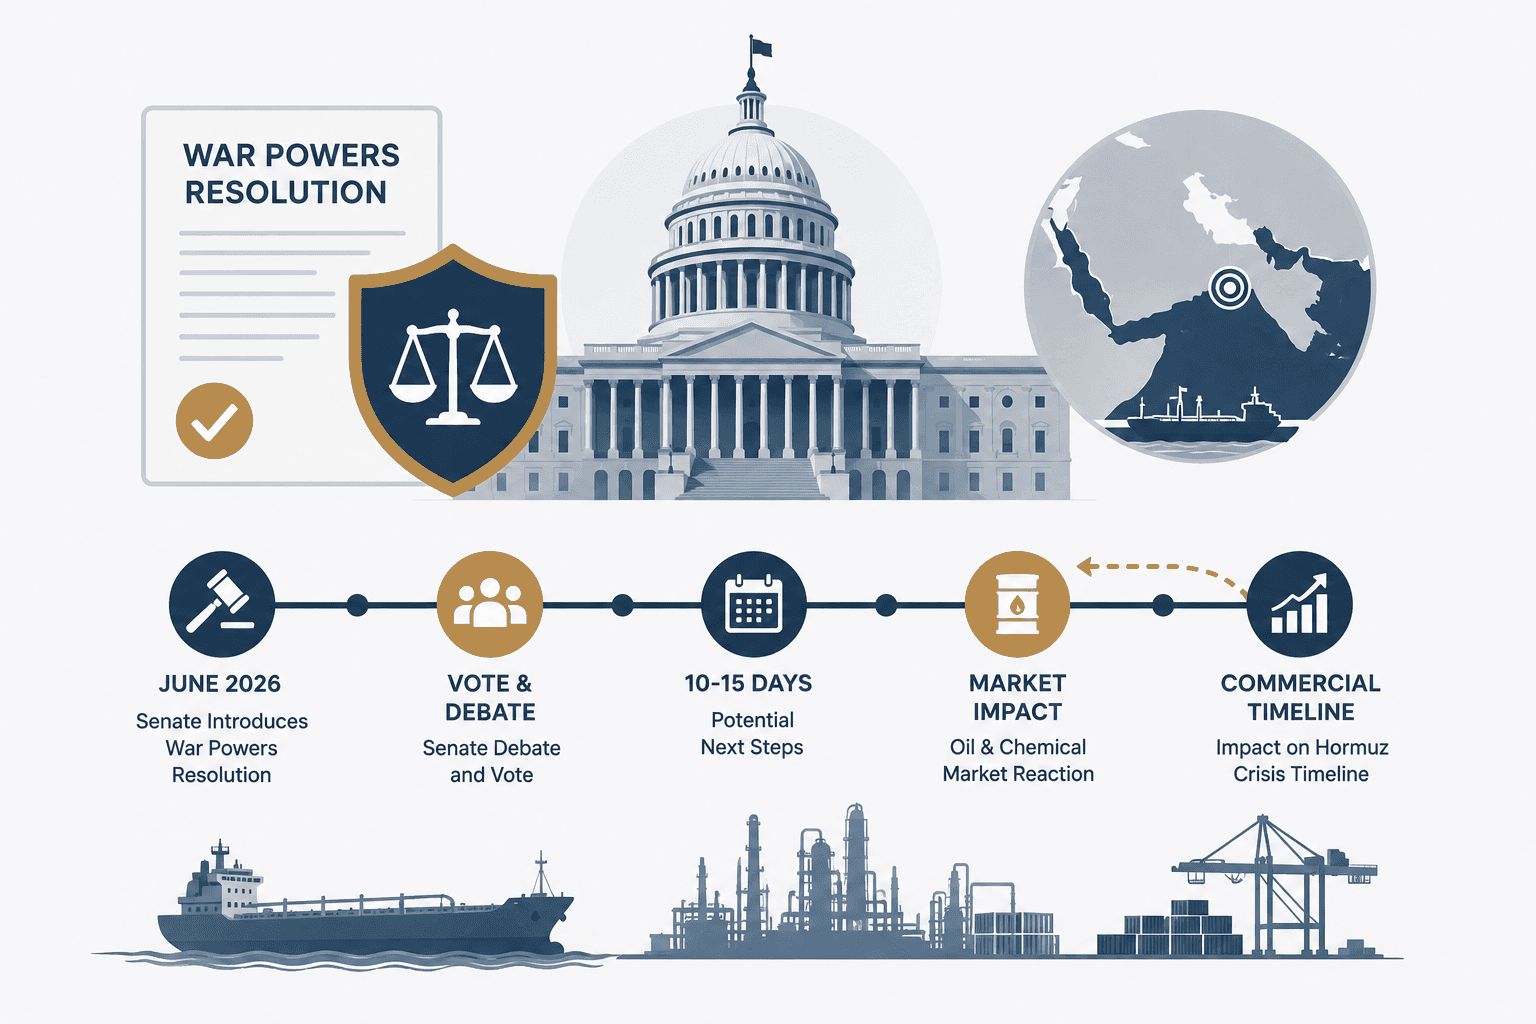
US Senate War Powers Resolution: What It Means for the Hormuz Crisis Commercial Timeline
The US Senate’s war powers resolution against Trump’s Iran conflict strategy may accelerate diplomatic pressure around the Hormuz crisis. For chemical markets, faster political de-escalation could mean quicker supply chain recovery and a more positive H2 2026 outlook.
The Paradox of June 29, 2026: Why Brent Is Below Pre-War Levels Despite Active Drone Strikes
Brent crude has fallen below pre-war levels despite active military escalation in the Gulf, creating a rare market paradox. For chemical procurement teams, falling feedstock costs and unresolved logistics risk are sending completely opposite signals into H2 2026.
Don't miss out on our updates! Subscribe to our newsletter now
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.